Surendra Jauhari
SEBI Registered Investment Advisor - INA000021474
The Label Tax
What SEBIs Rules Reveal About Indian Mutual Funds
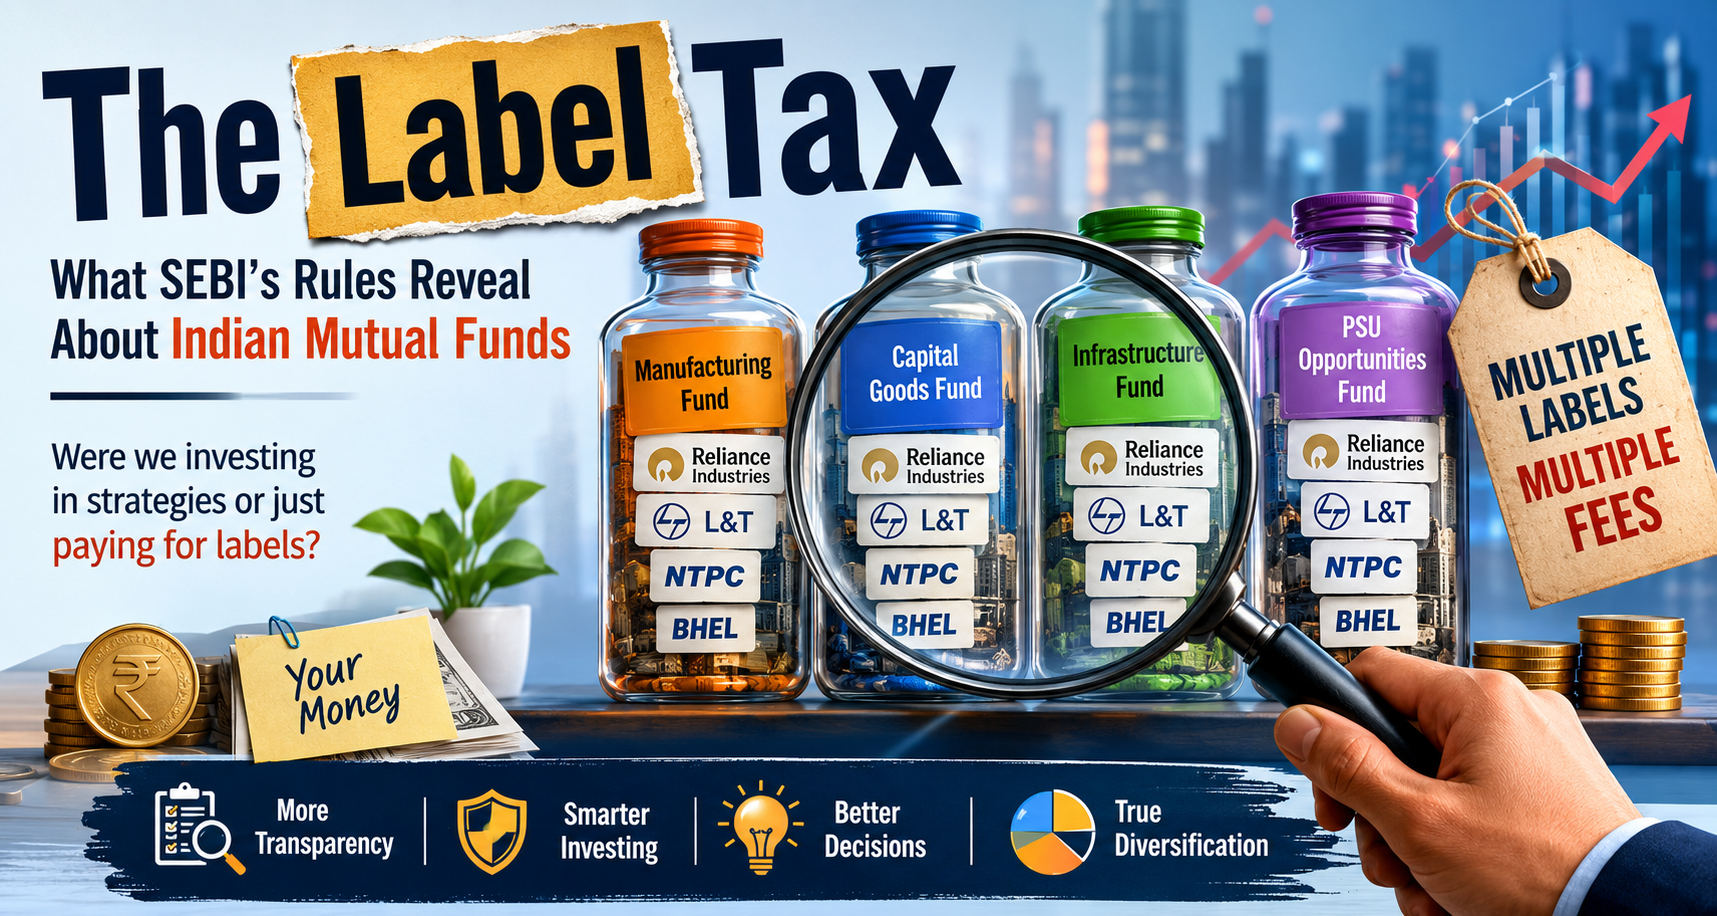
Let us look at the products of any mutual fund company. They have types of funds like Manufacturing fund, Capital Goods fund, Infrastructure fund and PSU Opportunities fund. Now if we open their portfolios, we will find that Reliance Industries is in all four Mutual Funds. So is L&T. So is NTPC. So is BHEL. This means that four different investment ideas are actually the same with four fees and they are about investing in Indias large industrial companies. This is not a mistake it is how the Indian Mutual Fund business works. SEBI acknowledged the issue through its July 2025 consultation paper and addressed it in the February 2026 circular.
We have been calling this diversification for a time. It is worth asking what we were actually buying when we invested in Mutual Funds.
The Exemption That Made Sense
In October 2017 SEBI issued a rule that said there can be one scheme per category. This rule applied to Cap, Mid Cap and Small Cap funds, which were defined by market-cap rank at that time. This rule was a success. The total number of folios rose from 5.54 crore in FY17 to 7.22 crore within a year. People were less confused and more people started investing in Mutual Funds.
The 2017 circular exempted sectoral and thematic Indian Mutual Funds from the one-scheme rule. The logic was reasonable. A thematic Indian Mutual Fund is supposed to be different from another Indian Mutual Fund. What nobody thought about was what a mutual fund company would do when it found out that it can launch Mutual Funds in this category.
They launch Mutual Funds.
They create labels for the stocks in Mutual Funds.
How the Loophole Got Found
Between 2020 and 2024 India's mutual fund industry went through a boom. New fund launches rose from 81 in 2020 to 239 in 2024. The amount of money raised more than doubled, from ₹53,703 crore to over ₹1.18 lakh crore. By FY2025 52 of the 70 equity NFOs launched that year were sectoral or thematic. They alone pulled in ₹73,633 crore, which's three times what the same category raised the year before.
This is what should bother every investor: a category growing to 15.45% of equity AUM while generating 74% of all equity NFOs is not a sign of investor demand. It is a sign of arbitrage. Mutual fund companies were not discovering ways to invest in the economy. They were discovering labels for the stocks in Mutual Funds.
Nowhere is this clearer than in defence funds. India's listed defence companies are HAL, BEL, BEML and a few private suppliers. When three or four mutual fund companies launch defence-themed Indian Mutual Funds within months of one another the resulting portfolios are not going to be different.
SEBI Says It Out Loud
By July 2025 SEBI stopped pretending this was fine. In its consultation paper the regulator wrote: "In case of some schemes there was an overlap of portfolios. It was therefore felt necessary to introduce limits to the industry to avoid schemes with portfolios."
1. SEBI is confirming that within-category overlap between Indian Mutual Funds from the mutual fund company was routinely running 25% to 55%.
2. Large-cap fund pairs from the fund house separately were overlapping 70-80%.
Seven months later SEBI acted. The February 26 2026 circular put a 50% ceiling on portfolio overlap between any scheme and any other equity scheme from the AMC. Existing non-compliant schemes get three years to comply.
This is a deal. It is more than the headline number suggests. Scheme mergers in India have historically been reactive. SEBI has now built a forcing mechanism directly into the regulation itself.
The Circular Isn’t the Event. August Is.
Here’s what most coverage of this story has gotten backwards: the February circular is the rulebook, not the moment that matters. The moment that matters is August 2026 when every mutual fund company in India will be required to publish category-overlap data on its website every month.
Why does this matter more than the rule itself? Because now identifying overlap requires a third-party calculator. After August it requires nothing than opening a mutual fund company’s website.
What the Rule Quietly Leaves Alone
None of this should be mistaken for a fix.
The 50% cap applies to schemes and to value/contra pairs. It does not apply to flexi-cap funds from the AMC. The rule also measures overlap within an AMC.
There is also a counterargument worth taking seriously: compliance is not free. Mutual fund companies now have to build systems to calculate overlap on a basis publish disclosures and potentially execute scheme mergers.
Know How Healthy Your Portfolio Really Is
Upload your mutual fund or stock portfolio and receive a free portfolio dashboard. Unlock a comprehensive audit with portfolio diagnostics, risk analysis, overlap detection, and detailed educational insights.
The Force That Was Coming Anyway
Here is the truth: the label tax was already becoming commercially unsustainable before SEBI stepped in.
Passive fund AUM grew 31% year-on-year through FY2026 now accounting for 18% of industry assets. Investor awareness of index funds has reached 76% in surveys. 68% Of investors have now put money into least one passive product.
SEBI’s overlap rule did not create this pressure. It accelerated a clock that was already running.
What We’re Really Paying For
Strip away the categories, the numbers, the compliance dates and the question underneath all of it is simple: were we ever buying investment strategies? Were we buying labels for Mutual Funds?
The data gives an answer to that question that any AMC marketing document does not.
Investors who set up SIPs in three Mutual Funds in 2023 are still investing in those Indian Mutual Funds today.
This is because SIPs do not automatically adjust or rebalance.
SIP investments now make up 21% of the assets under management in the industry.
That is a lot of money.
Many investors are unknowingly investing in Mutual Funds.
This is not a mistake.
It is millions of people investing in Indian Mutual Funds year after year.
They are doing this because the fund label said something that the actual portfolio of Indian Mutual Funds did not.
The 2017 circular showed that exemptions can be taken advantage of.
The 2026 circular is SEBI closing the exemption it did not close earlier.
When the overlap numbers are made public in August, we will see if Indian investors start asking questions.
They will want to know what they are paying for.
The regulator cannot make investors ask these questions.
When investors see the facts will they demand answers, about Indian Funds?
Disclaimer
Investments in securities market are subject to market risks. Read all the related documents carefully before investing
Registration granted by SEBI, membership of BASL and certification from NISM in no way guarantee performance of the intermediary or provide any assurance of returns to investors.
This article is published solely for educational and informational purposes and is intended to enhance investor awareness regarding developments in the Indian mutual fund industry.
The views, analysis, and interpretations presented are based on publicly available information, regulatory publications, and industry data available at the time of writing. The article should not be construed as investment advice, investment research, a recommendation, or a solicitation to buy, sell, or hold any security, mutual fund, or financial product.
Examples of securities, mutual funds, sectors, or investment categories mentioned in this article are provided purely for illustration to explain the regulatory framework and should not be interpreted as recommendations or views on their future performance.
Past performance, historical portfolio holdings, regulatory changes, and market trends are not indicative of future results. Investors should evaluate their own financial objectives, risk tolerance, investment horizon, and consult a SEBI Registered Investment Adviser before making investment decisions.
The author and publisher disclaim any liability arising from the use of the information contained in this article.
Sources
SEBI — Consultation Paper on “Categorization and Rationalization of Mutual Fund Schemes,” July 18, 2025 (sebi.gov.in).
SEBI — Circular No. HO/24/13/15(2)2026-IMD-RAC4/I/5764/2026, “Categorization and Rationalization of Mutual Fund Schemes,” February 26, 2026 (sebi.gov.in).
SEBI — “Categorization and Rationalization of Mutual Fund Schemes,” Circular dated October 6, 2017 (SEBI/HO/IMD/DF3/CIR/P/2017/114).
AMFI — Annual Report FY2025 and Monthly Notes, including March 2025 and May 2026 data (amfiindia.com).
S&P Dow Jones Indices — SPIVA India Mid-Year 2025 and Year-End 2025 Scorecards (spglobal.com).
Motilal Oswal Mutual Fund — Investor and distributor survey, 2025 (3,000+ investors, 120 distributors).
Mondaq / Finseclaw — “SEBI’s 2026 Mutual Fund Regulations Overhaul,” March 26, 2026.
RMLNLU Law Review — “Implications of SEBI Categorisation and Rationalisation of Mutual Fund Schemes” (2018/2020).
sum.money / BharatSaver — mutual fund portfolio overlap data; Whalesbook